10 Practical Ways to Stretch Your Money in Nigeria Right Now
With prices of food, transport and rent weighing on households, small habits can protect your budget. Here are ten that work.
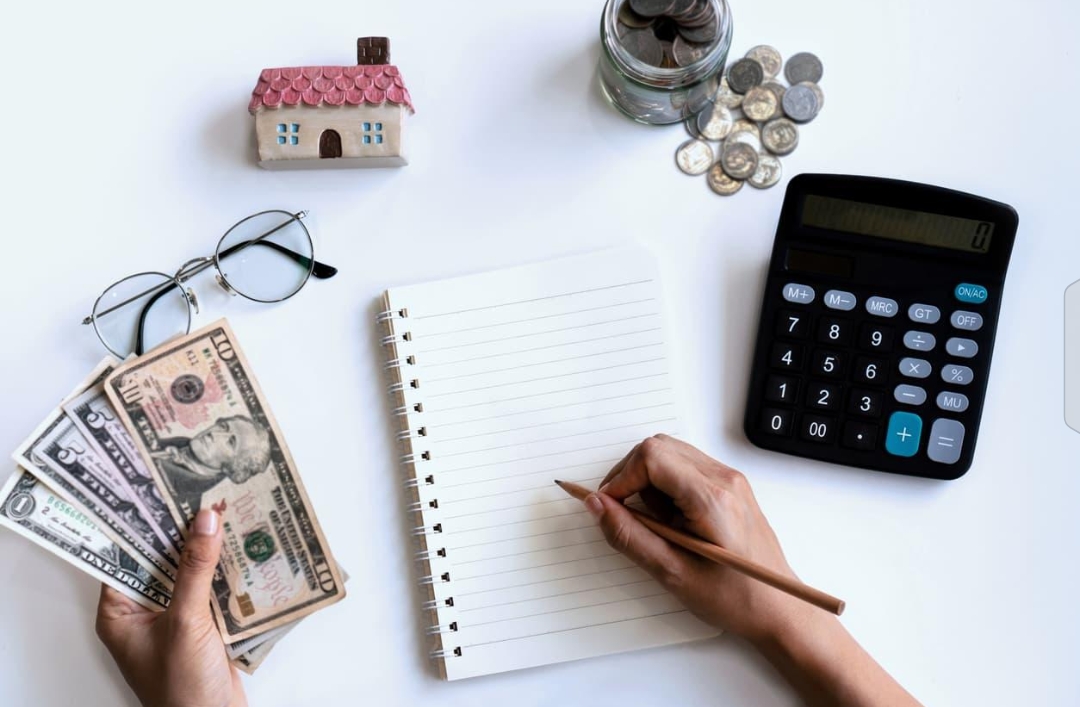
Rising costs have forced many Nigerian families, students and young professionals to rethink how they spend. You can't control market prices, but you can control how your money moves. The ideas below are practical, cost little to start, and work whether you earn a salary, run a small business or live on an allowance.
First, know where your money goes
- Track every naira for 30 days. Use a notebook, a notes app or a free budgeting app. Write down every expense, even small ones like airtime, snacks and transfer charges. Most people are surprised: small daily spending often adds up to more than their biggest single bill. For example, ₦1,500 a day on snacks and drinks is ₦45,000 a month. Once you see your numbers, you know where to cut.
- Split your income into three buckets. A simple starting point is needs, wants and savings. Needs are rent, food, transport, school fees and bills. Wants are outings, new clothes and entertainment. Savings come first, not last. If you can only manage 10% savings at the start, begin there and raise it when you can. The exact percentages matter less than having a plan before the money comes in.
Cut the biggest costs first
- Plan your meals weekly. Food is the largest expense for most households. Decide your meals for the week, check what you already have, and write a shopping list. This stops impulse buying and reduces waste. Cooking a large pot of soup or stew twice a week and portioning it saves both money and fuel or gas.
- Buy staples in bulk and share the cost. Rice, beans, garri, oil, tomatoes and onions are usually cheaper per unit when bought in larger quantities. If you can't afford a full bag, split with a neighbour, colleague or roommate. Buy non-perishables when prices dip, and avoid buying perishables in bulk unless you can store them.
- Compare markets and shop at the right time. Open markets often beat supermarkets on fresh produce. Visit more than one stall before buying, and consider late-afternoon shopping, when some sellers lower prices to clear stock.
- Cut transport costs. Walk short distances, share rides, combine errands into one trip, and avoid peak hours when fares rise. If you work from home on some days, plan your week so you travel less.
Reduce the quiet leaks
- Manage data and airtime. Compare data plans, avoid auto-renewal if you don't need it, and turn off background app updates on mobile data. Use Wi-Fi at home, school or work when you can. Small savings here repeat every month.
- Repair before you replace. Shoes, bags, phones and small appliances can often be fixed for much less than the price of a new one. Keep a trusted repairer's number. When you do replace, buy quality that lasts rather than cheap items you'll buy again.
Build a safety net and grow income
- Start a small emergency fund. Aim first for one week of basic costs, then two, then a month. Keep it separate from your spending account so you're not tempted to use it. An emergency fund keeps one bad week from becoming debt.
- Look for a second income stream, and avoid get-rich-quick traps. Skills like design, writing, tutoring, repairs, farming on a small scale or reselling can add income. Be careful with "investment" schemes that promise fast, guaranteed returns. If an offer sounds too good to be true, it usually is. Check whether the company is registered and regulated, and never invest money you can't afford to lose.
A simple monthly routine
Day 1 of the month: write your budget and move savings out first.
Weekly: plan meals and set a spending limit.
End of month: compare what you planned with what you spent, and adjust.
Bottom line: No single habit will solve high costs. But tracking your spending, planning meals, cutting leaks and building even a small savings cushion can make a real difference over a few months. Start with one or two ideas this week and add more as they become habits.